- Futures contracts (/ES, /NQ, /MES, /CL) qualify as IRC §1256 contracts — typically receive the 60% long-term / 40% short-term split regardless of holding period.
- Futures are typically wash-sale exempt — sell at a loss, repurchase immediately, the loss is typically fully deductible.
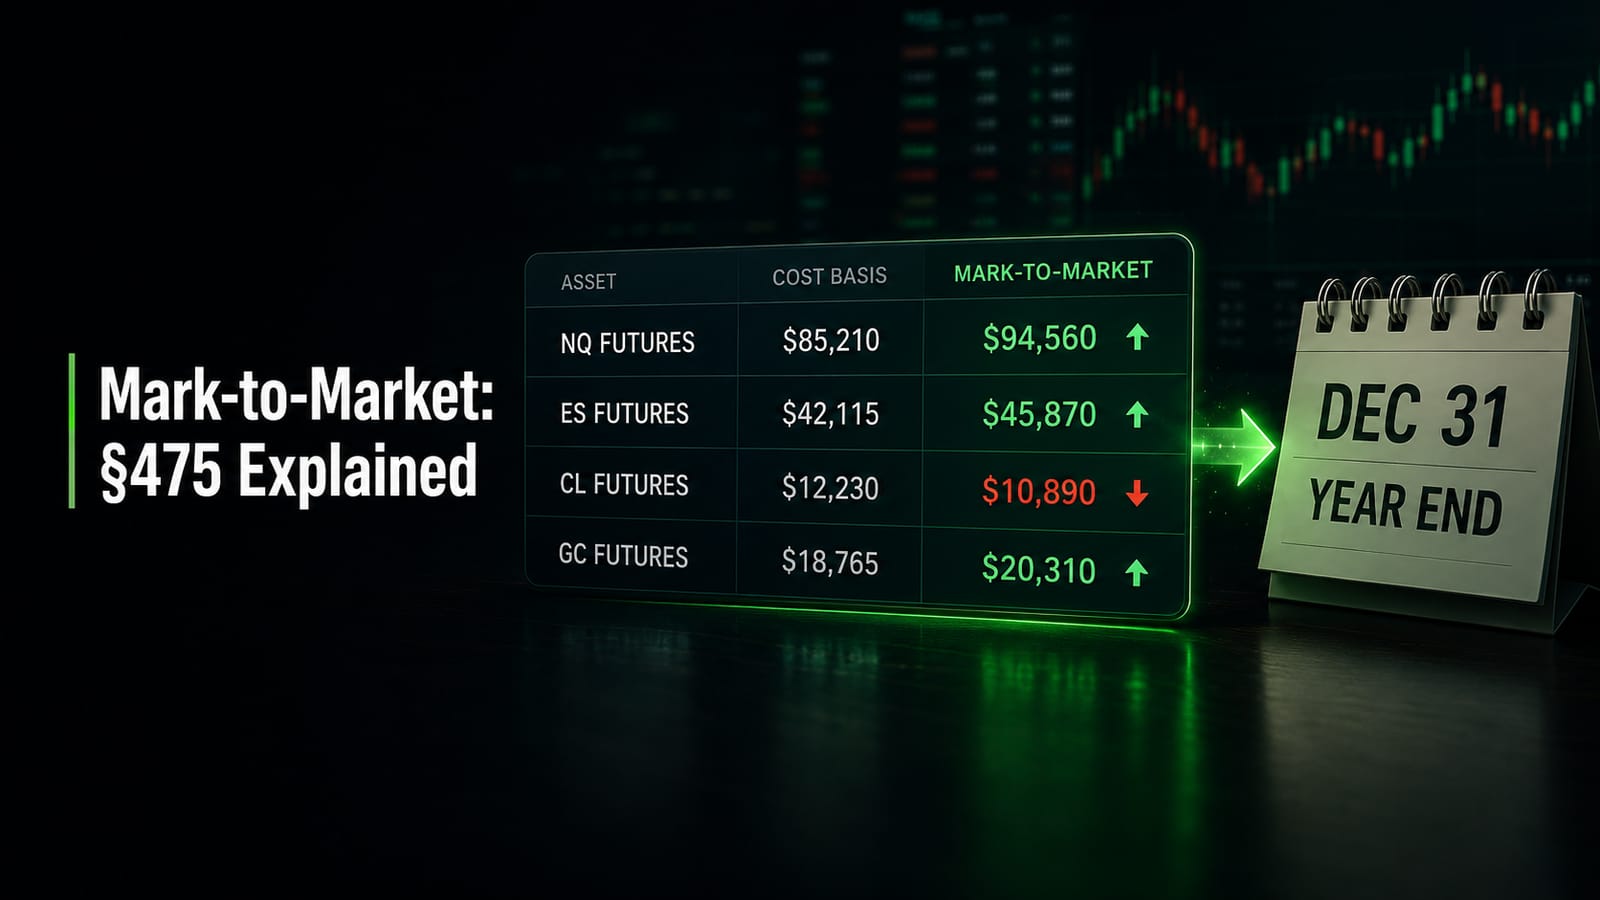
- Automatic mark-to-market at year-end means open §1256 positions are typically treated as sold on December 31. No separate election needed.
- Reported on Form 6781, not Schedule D. §1256 losses can typically be carried back 3 years to offset prior-year §1256 gains.
- Trading a prop firm account is typically not the same thing. Section 1256 applies to contracts you hold in your own account. A funded-account payout is generally compensation for a service, so it is usually ordinary income rather than 60/40 — see prop firm taxes.
- Every situation varies — entity choice, mixed-instrument trading (futures + stocks + options), and state residency all affect the picture. A CPA who specializes in trader taxation can confirm what applies.
Futures traders have a significant tax advantage over stock and options traders — one written directly into the tax code. It's called Section 1256, and if you trade ES, NQ, CL, GC, or most other exchange-traded futures, understanding this rule can save you thousands every year. One exception is worth knowing up front: single stock futures — the single-name contracts CME began listing in July 2026 — are securities futures contracts, which are typically excluded from Section 1256 for non-dealer traders, so they generally do not receive 60/40 treatment.
What Is Section 1256?
Section 1256 of the Internal Revenue Code covers certain regulated financial contracts, including:
- Regulated futures contracts (ES, NQ, CL, GC, ZB, etc.)
- Foreign currency contracts
- Non-equity options (index options like SPX, NDX, RUT)
- Dealer equity options
- Dealer securities futures contracts
These contracts receive special tax treatment not available to regular stocks or equity options.
The list above tracks the IRS's own definition. The authoritative version — including the current form, the line-by-line instructions, and the 3-year carryback election — sits on the IRS's About Form 6781, Gains and Losses From Section 1256 Contracts and Straddles page. Whether a specific contract qualifies can turn on facts particular to the instrument, so most traders confirm borderline cases with a CPA.
The 60/40 Rule — The Core Advantage
All gains and losses on Section 1256 contracts are automatically split 60% long-term / 40% short-term — regardless of how long you actually held the position.
This matters enormously. Most futures traders hold positions for minutes or hours. Under regular rules, those would all be short-term gains taxed at ordinary income rates (up to 37%). Under Section 1256, 60% of every gain is automatically long-term — taxed at preferential capital gains rates (0%, 15%, or 20%).
A futures trader in the 35% federal bracket earns $100,000. Under regular short-term rules: $35,000 tax. Under Section 1256 (60/40): approximately $26,800 in federal tax — a savings of $8,200 on a single year's gains, just from trading the right instrument.
Futures Traders Are Exempt from Wash Sale Rules
Section 1256 contracts are explicitly exempt from the wash sale rule. You can sell a futures contract at a loss and immediately rebuy the same contract without the loss being disallowed. This is a major advantage over stock traders who must wait 31 days.
The 3-Year Loss Carryback for Futures
Section 1256 losses have a unique feature not available to most traders: you can carry losses back up to 3 years. This means if you have a bad year in futures trading, you can amend prior tax returns and get refunds for taxes you already paid — going back three years.
Example: You had large futures gains in 2023, 2024, and 2025 — paying substantial taxes. In 2026, you have a large loss. You can carry that loss back to 2023 and receive refunds for all three prior years.
The carryback can only offset net §1256 contract gains in those prior years. It is not a general loss carryback. If 2023 to 2025 were years of W-2 income, or stock gains, or prop firm payouts, there is nothing for a §1256 loss to reach — it needs §1256 gains to land on. That single condition is why the carryback is powerful for a consistent futures trader and useless for someone whose futures loss is their first futures year.
- It is an election, and it is made on Form 6781 — by checking box D and entering the amount carried back.
- You then claim it on Form 1045, Application for Tentative Refund, or on amended returns for the prior years. Form 1045 is the faster route and has its own deadline.
- It goes to the earliest of the three years first, then forward — you do not get to choose the most useful year.
- It cannot create or increase a net operating loss in the carryback year, which caps how much of it lands.
- The loss keeps its 60/40 character in the carryback year, so it offsets at the blended rate rather than at an ordinary one.
- Corporations, estates and trusts cannot make this election. If you trade through an entity, check which one you are before planning around this.
Anything not carried back is carried forward as a capital loss under the ordinary rules. A CPA experienced in futures taxation is the right call on the mechanics — particularly on whether Form 1045 or an amended return is the better route in your case.
How to Report Section 1256 Gains and Losses
Section 1256 contracts are reported on Form 6781 — "Gains and Losses from Section 1256 Contracts and Straddles." Your broker should provide a 1099-B showing your total Section 1256 contract gains and losses for the year.
The Form 6781 automatically calculates your 60/40 split and flows the results to Schedule D.
Futures vs Stocks: Tax Comparison
| Feature | Stock Trading | Futures Trading (§1256) |
|---|---|---|
| Short-term gains tax rate | Up to 37% (ordinary) | Blended ~26.8% max |
| Wash sale rule applies | Yes | No |
| Loss carryback | No (forward only) | Yes — 3 years back |
| Holding period required for LTCG | 1 year minimum | Automatic 60% LTCG |
| Mark to market at year-end | No (unless MTM elected) | Yes — automatic |
Which contracts does this actually cover?
Section 1256 turns on the contract, not on the strategy, so it is worth knowing where your own instruments sit. Four companion pages go family by family rather than repeating the mechanics here:
- ES, NQ, MES and MNQ taxes — the equity index contracts, including whether the micro versions are treated differently (generally not), and why single stock futures are typically excluded from §1256 despite the name.
- Gold and crude oil futures taxes — GC and CL on COMEX and NYMEX, what physical delivery and rolling mean in practice, and the comparison most gold traders have backwards: a physically-backed gold ETF is commonly taxed at the 28% collectibles rate, generally worse than the ~26.8% §1256 blend on the futures contract.
- Treasury futures taxes — ZB, ZN, ZF and ZT on the CBOT, and the point most rate traders get wrong: the state tax exemption on Treasury interest generally does not follow you into the futures contract, because the contract pays no coupon. Also covers the deliverable basket and why a cash-versus-futures basis trade is a professional-only position.
- Crypto futures taxes — BTC, MBT, ETH and MET, and the comparison that matters more than any of them: the same bitcoin exposure is taxed three different ways depending on whether you held a listed future, spot coin, or a perpetual. If you want 60/40 on crypto, the venue is the lever rather than the strategy.
The tax answer does not vary within a family — MNQ is taxed like NQ, ZF like ZB, and MBT like BTC — which is why these are four pages rather than a page per ticker.
What §1256 does not reach is worth knowing too. The section turns on a qualified board or exchange, which means an SEC-registered exchange or a CFTC-designated contract market. A perpetual future on an offshore or on-chain venue is outside that definition however much it behaves like a futures contract — and even a US-listed perp runs into the §1256(b)(2)(B) swap exclusion because of its funding mechanism. If part of your book is perps, that is a different analysis, not this one.
Are prop firm payouts taxed the same as your own futures trades?
Usually not. Section 1256's 60/40 split applies to regulated futures contracts held in your own account. When a funded account belongs to a prop firm, the payout is generally treated as compensation for a service — ordinary income, commonly self-employment income on Schedule C — rather than a §1256 gain.
This is one of the most frequently confused points in trader taxation, and it cuts both ways: a trader who reports prop payouts as 60/40 gains may be understating tax, while a trader who reports their own futures profits as ordinary income may be overpaying. Traders who do both in the same year typically track the two activities separately. Full detail on the payout side is in the prop firm taxes guide, and the firm-by-firm reporting differences are covered on the individual firm pages.
Year-end marking is automatic, and it can tax a position you still hold
This is the most common surprise in §1256, and it has nothing to do with the §475 election people confuse it with. §1256 marks your open contracts to market at the end of the year by operation of law. There is no election, no form to opt in, and no way to defer it: a contract you still hold on the last business day of the year is treated as if you sold it at fair market value that day, and the resulting gain or loss goes on that year's return.
You can owe tax on a contract you never closed. A trader who is up substantially on an open position in late December has a real, reportable gain for that year even though no money has been taken off the table — and if the position reverses in January, the loss falls in the following tax year. The economics net out eventually; the cash flow does not.
It cuts the other way too, and that half is useful: an open position carrying a loss at year end gives you that loss now, without closing the trade.
Two things follow. When the position is eventually closed, the gain or loss is measured from the marked value, not from your original cost — the adjustment prevents double counting, and missing it is a real reporting error. And this is a December planning item, not an April one: the only point at which the year-end mark can be influenced is before the year ends.
Note how this differs from the §475 mark-to-market election, which traders routinely conflate with it. §1256's marking is automatic and does not change the character of your gain — it stays 60/40 capital. A §475 election is voluntary, applies to a class of positions, and makes gain ordinary. One is a timing rule you already live under; the other is a character election you have to file for.
Mixed straddles: where futures and non-futures positions collide
If you hold a §1256 contract and an offsetting position that is not a §1256 contract — index futures against an index ETF, futures against the underlying, futures against equity options — you may have a mixed straddle: a straddle in which at least one, but not all, of the positions is a §1256 contract.
This matters because the two halves of the position otherwise live under different tax regimes. The futures leg is marked at year end and taxed 60/40; the other leg is not. Left alone, the straddle loss-deferral rules can suspend a loss on one leg while the gain on the other is fully taxed — the mismatch the straddle rules exist to prevent, applied to a position you entered for ordinary hedging reasons.
The tax code's answer is a choice of three elections, and you may make only one for a given straddle:
| Election | What it does | The catch |
|---|---|---|
| Mixed straddle election §1256(d) | Turns the mark-to-market rules off for the §1256 contracts in the straddle, so both legs sit under one regime | Applies to all later years and cannot be revoked without IRS consent. This is the one people make without realising how long it lasts. |
| Identified mixed straddle straddle-by-straddle, under the §1092 temporary regulations | Treats each identified straddle on its own, netting within it | Requires identification by the earlier of the close of the day the straddle is established or the time a position is disposed of. Miss the identification and the election is simply unavailable. |
| Mixed straddle account | Groups all positions in a designated class of activity into one account, netted daily and marked to market at the close of each business day | A real accounting commitment. Appropriate for a systematic hedging programme, not for one trade. |
The identification requirements run from the day the straddle is established — on the day the first §1256 contract forming part of the straddle is acquired, each position has to be clearly identified as part of it. This is the rare tax item you cannot fix at filing. Everything else on this page can be sorted out in March; a mixed straddle election generally cannot, because the window closed on the day you put the trade on.
So if you are putting on an offsetting position across the §1256 line, the conversation with a CPA belongs before the trade. Which election fits — or whether none of them does and you accept the straddle rules — depends on the size of the position, how long you intend to hold it, and whether this is one hedge or a programme. We are not going to pick for you from a web page, and anyone who does is guessing about facts they cannot see.
Straddle treatment is also the reason cash-versus-futures basis trades are a professional-only position rather than a clever retail one.
Common Mistakes Futures Traders Make
- Not realizing Section 1256 treatment is automatic — some traders incorrectly report futures as regular capital gains
- Missing the loss carryback opportunity — this requires an active election and amended returns
- Confusing equity options (not §1256) with index options (§1256) — SPX options are §1256; AAPL options are not
- Not keeping track of end-of-year open positions — futures are marked to market on Dec 31 even if you haven't closed them
Frequently Asked Questions
What is the Section 1256 tax advantage for futures traders?
Section 1256 contracts including ES, NQ, CL, and GC futures are automatically taxed at a 60/40 blended rate — 60% long-term capital gains and 40% short-term — regardless of how long you held the trade. This results in a maximum federal rate of approximately 26.8% instead of 37%.
Are futures traders subject to wash sale rules?
No. Section 1256 contracts are exempt from wash sale rules, which is a significant advantage over stock and options traders.
Can futures traders carry back losses?
Yes. Section 1256 losses can be carried back three years to offset prior gains, potentially generating tax refunds on taxes already paid.
Not Sure Where You Stand on Taxes?
Answer 8 quick questions. Get a personalized AI summary of your tax exposure, missed deductions, and what you should do next — reviewed by a real CPA.
Get My Free Tax Snapshot →Dig deeper into the adjacent topics most relevant for active traders: